Loading homes
Buy
Find the home that fits the life.
Every home on the market in the areas I work, live from the MLS and refreshed through the day. Save the ones you like and I’ll keep you posted. And when you’re ready to write, you’ll have an Accredited Buyer’s Representative® in your corner — more than a decade on the buyer’s side of the table.
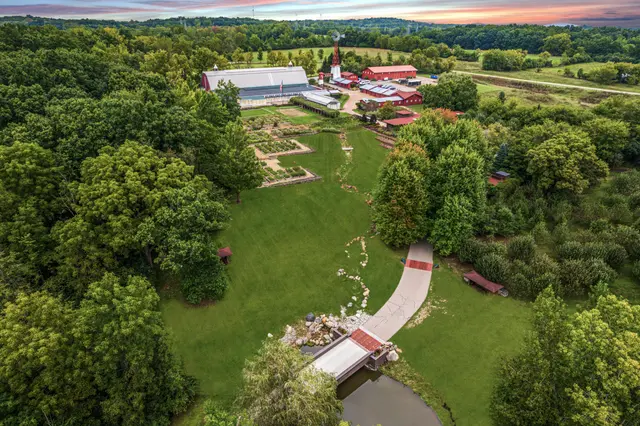 Active
$13,560,000
5200 Turtle Point Drive, Ann Arbor, MI 48105
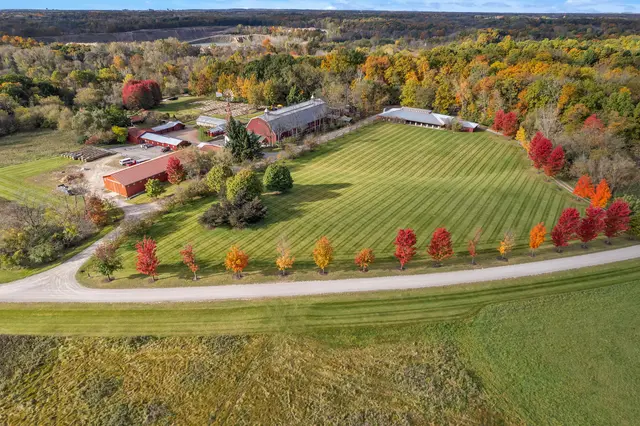 Active
$10,500,000
5105 Turtle Point Drive, Ann Arbor, MI 48105
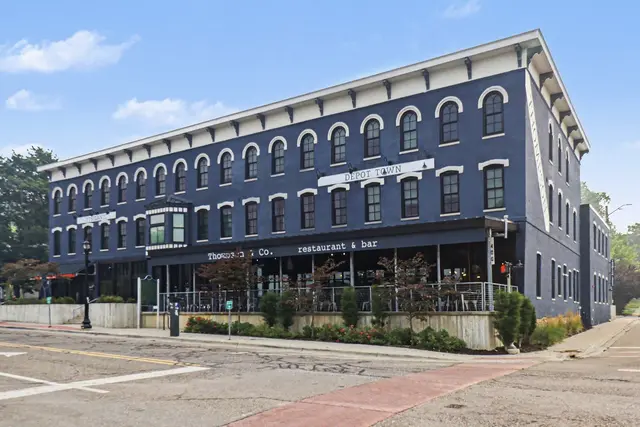 Active
$8,999,999Commercial
400 N River Street, Ypsilanti, MI 48198
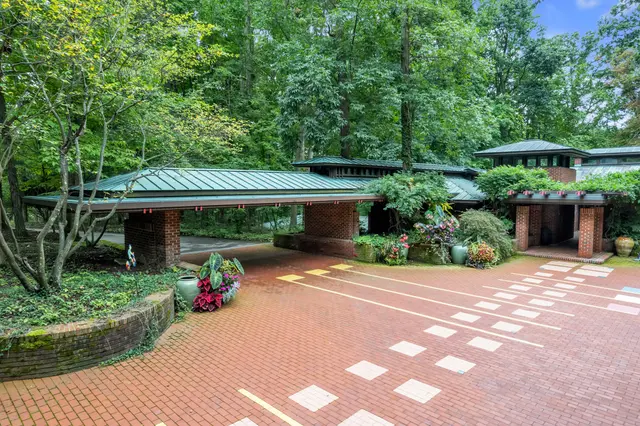 Active
$7,985,000
5140 Turtle Point Drive, Ann Arbor, MI 48105
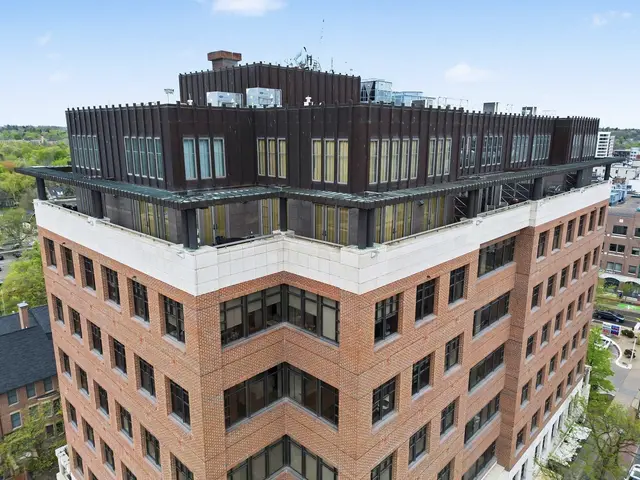 Active
$6,500,000
414 S Main Street 10, Ann Arbor, MI 48104
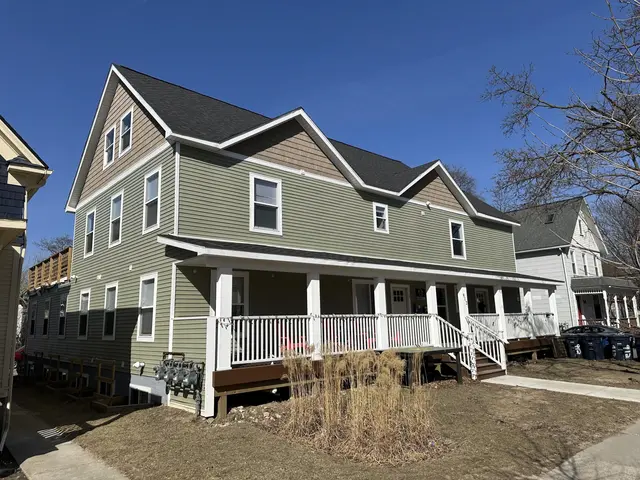 Active
$5,249,500
912 Mary Street, Ann Arbor, MI 48104
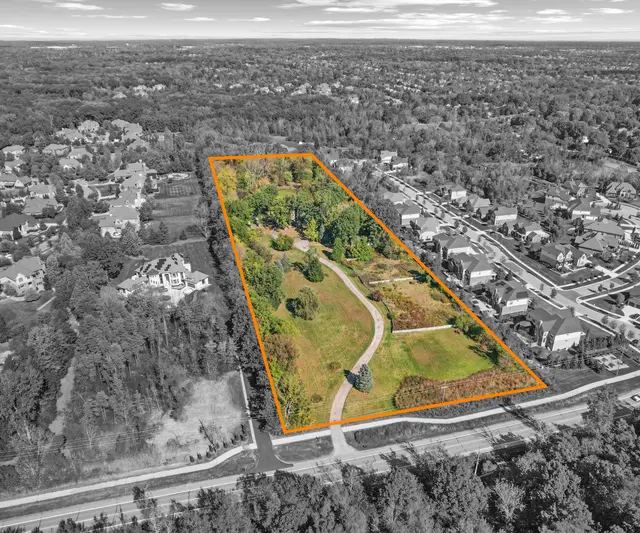 Active
$4,369,000
48000 W 8 Mile Road W, Northville, MI 48167
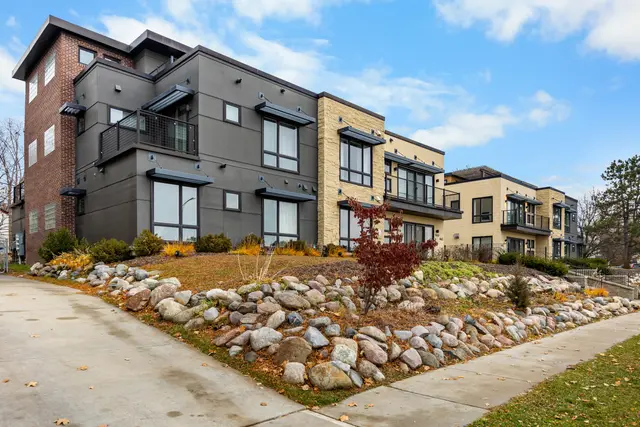 Active
$4,150,000
450-462 W Stadium Boulevard, Ann Arbor, MI 48103
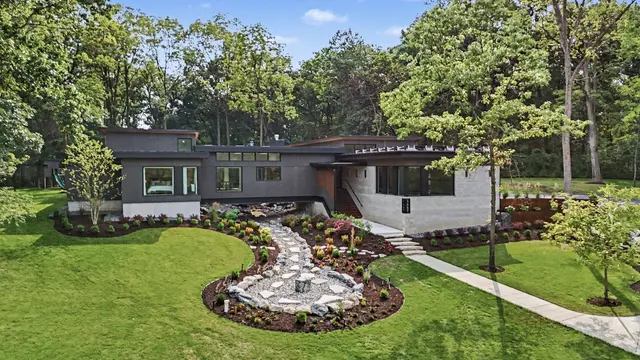 Active
$3,795,000
3657 Knoll Creek Court, Ann Arbor, MI 48105
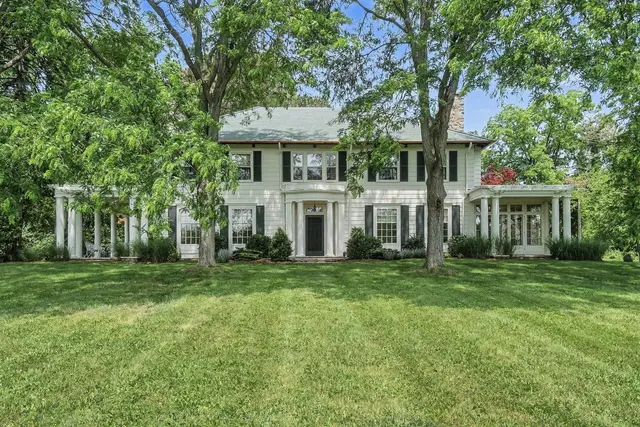 Active
$3,500,000
3215 W Dobson Place, Ann Arbor, MI 48105
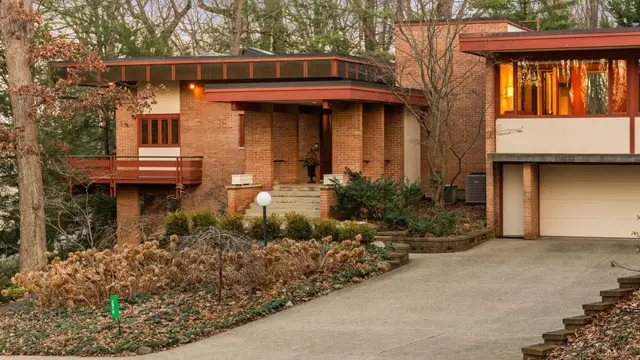 Active
$3,500,000
276 Indian River Place, Ann Arbor, MI 48104
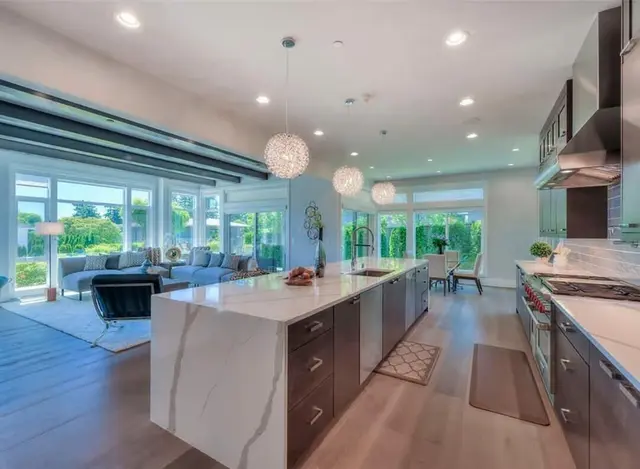 Active
$3,150,000
5902 Cherry Hill Road, Ann Arbor, MI 48105
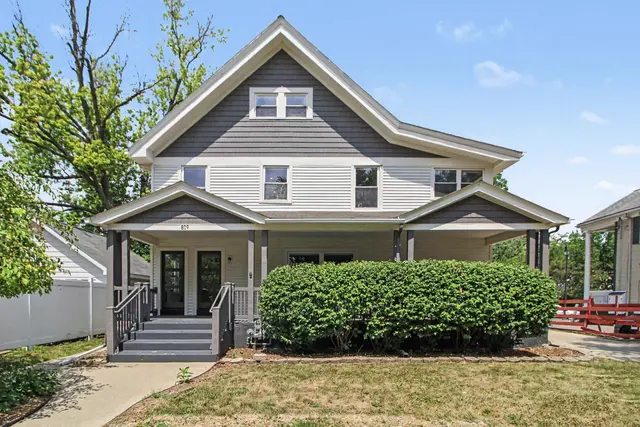 Active
$2,999,999Commercial
809 Henry Street, Ann Arbor, MI 48104
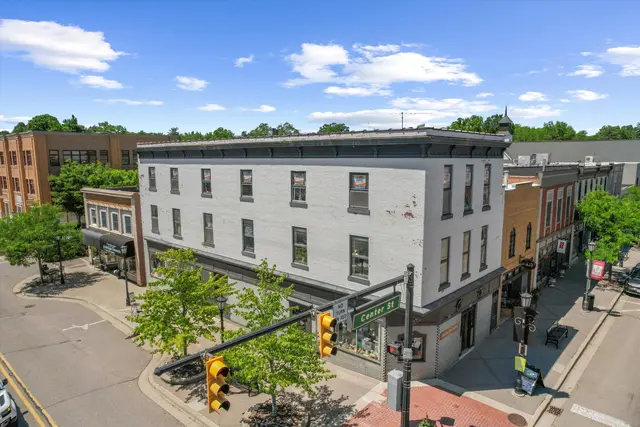 Active
$2,995,000Commercial
104 W Main Street, Northville, MI 48167
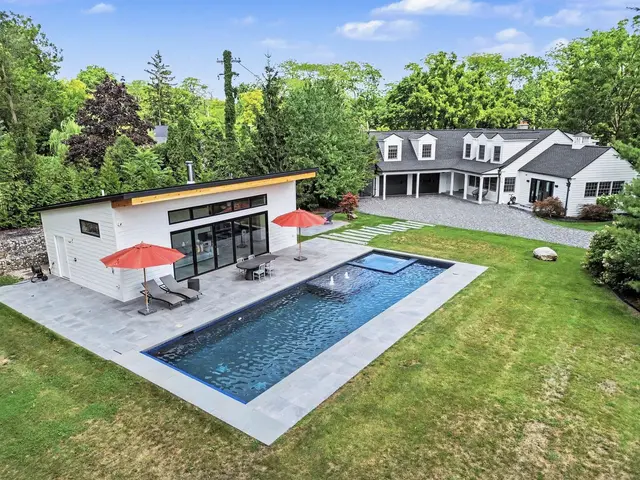 Active
$2,995,000
504 Burson Place, Ann Arbor, MI 48104
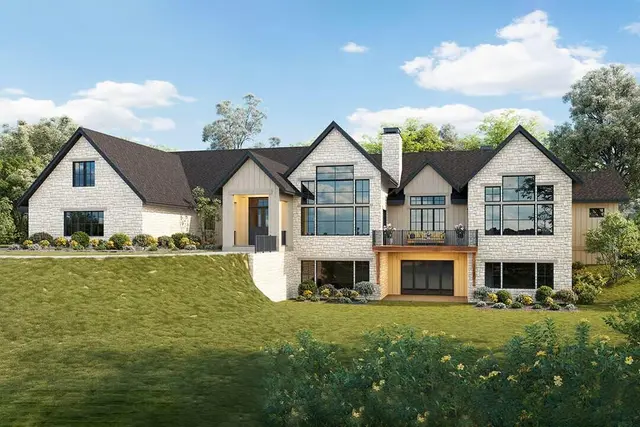 Active
$2,982,000
19277 Maybury Meadow Court, Northville, MI 48167
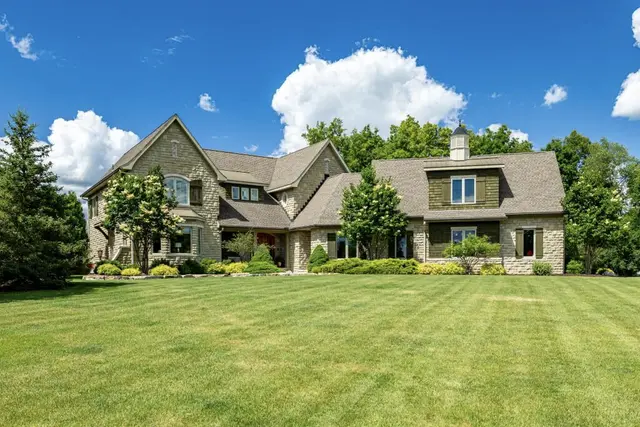 Active
$2,950,000
4370 Stonemeadow Court, Ann Arbor, MI 48103
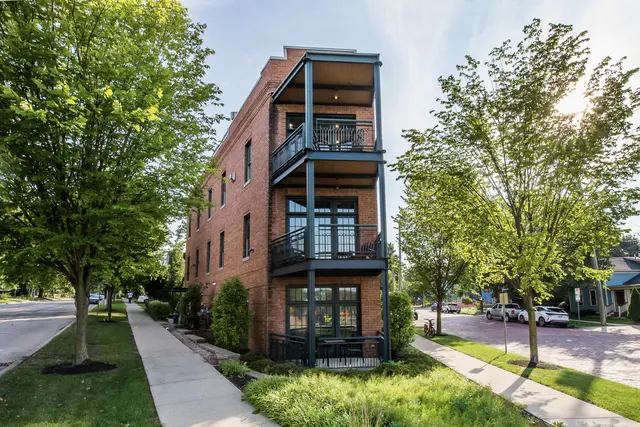 Active
$2,895,000
544 Detroit Street 201, Ann Arbor, MI 48104
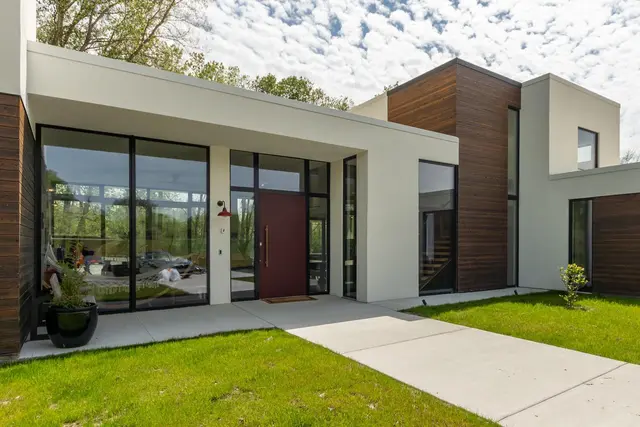 Active
$2,679,000
5980 Cherry Hill Road, Ann Arbor, MI 48105
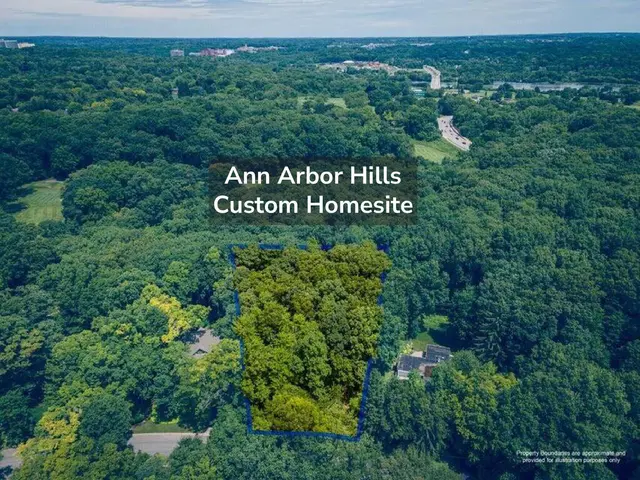 Active
$2,500,000
3081 Overridge Drive, Ann Arbor, MI 48104
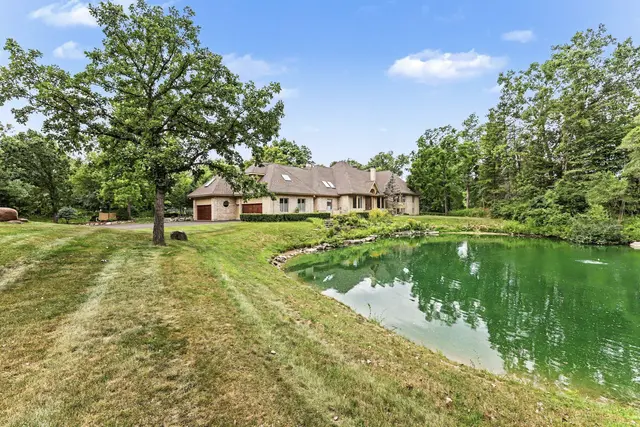 Active
$2,500,000
4911 Red Fox Run, Ann Arbor, MI 48105
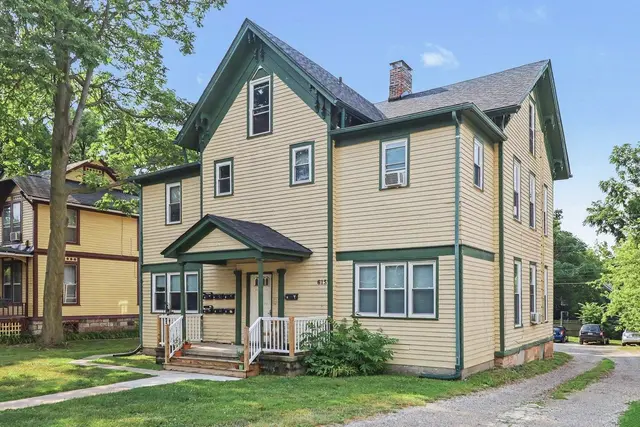 Active
$2,499,000
615 Pearl Street, Ypsilanti, MI 48197
 Active
$2,489,000
250 S Center Street, Northville, MI 48167
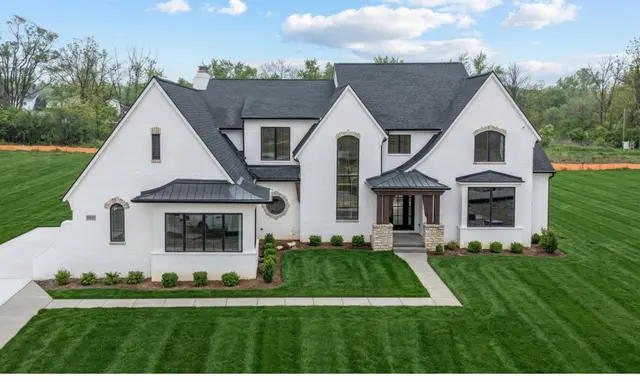 Active
$2,347,115
244 Barton Shore Drive 1, Ann Arbor, MI 48105
The market
Southeast Michigan right now.
779 homes for sale in Southeast Michigan. 778 sales, median $409K closed in the last 90 days.
Houses
466
For sale
$499K
Median asking
$234 per sq ft
218
Under contract
1,346
Sold, 6 months
median $473K
47%
Sold over asking
2.1
Months of supply
Condos
249
For sale
$355K
Median asking
$227 per sq ft
82
Under contract
463
Sold, 6 months
median $326K
20%
Sold over asking
3.2
Months of supply
- This week98 new listings · 63 price cuts · 62 went under contract
- Rent1-bed $1,663 · 2-bed $1,950 · 3-bed $2,650 · 4+-bed $3,575 a month at the median, over 167 rentals
| Month | Sales | Median |
|---|---|---|
| Apr 2026 | 291 | $428K |
| May 2026 | 347 | $465K |
| Jun 2026 | 380 | $445K |
| Jul 2026 | 352 | $425K |
| Aug 2026 | 288 | $403K |
| Sep 2026 | 228 | $411K |
| Oct 2026 | 46 | $373K |
From MichRIC listing data on this site, computed Oct 11 and refreshed with the feed.
How these are counted
The columns are houses and condos. Small multi-family, manufactured homes and the subtypes the feed leaves unplaceable are counted in the total above and in neither column, so the two columns do not add up to it. Land and farms are left out. “Over asking” means above the price a home was last listed at, not its original price, and is taken over the sales that carried one. Price per square foot divides by above-grade finished area where the MLS reports it and by the total finished area where it does not; each figure is labelled with the one it used, so two figures labelled differently are not measuring the same thing. Below 5 sales a figure gives the count without a median, and a single sale is given no figure at all.
How we work
You will always be informed, confident, and prepared for the next step.
We start with what you want and then we determine the best plan to acquire it. We look, we write, and we close — all with my expert guidance at every stage.
01
Define the property
Where, what, and a number that fits — house, condo, townhome, land, or a new build. We put that on paper so the search has a target. It does not have to be perfect on day one.
02
Know the number
Pre-approval before we write. A lender reads the file and tells us what it will support. I introduce options and keep the number in view so we tour inside a real budget, not a hopeful one.
03
We view together
We sign a written buyer agreement so the duties are clear. Then we view the properties together. I set the appointments, I am there for every showing, and I offer my guidance throughout.
04
The offer
This is strategy, not just a form. I advise on price, terms, and timing so the offer can compete, protect you, and serve your goals.
05
Due diligence
Inspections, insurance, appraisal, and title. We stay on track, negotiate and remedy any important deficiencies, and move forward accordingly.
06
Financing
Your lender carries this stretch through underwriting to a clear to close. The pace is largely set by you: whatever they ask for should go back as soon as possible.
After the offer
Accepted is not closed.
The work after a seller says yes is its own sequence. I keep it moving so the file arrives at the table in order.
Inspection
A professional inspection can uncover unknown issues, and specialty inspections can go deeper. You should receive a written report with all findings from your inspector. If something material shows up, the contingency is how we negotiate — or walk away.
Insurance
Coverage is ordered while the file is still moving. The carrier looks at the property’s claims history, which can change the premium and sometimes tells us what a disclosure did not.
Appraisal
If the purchase is financed, the lender’s appraiser sets a maximum value they will lend against. If it meets the contract price, we move forward. If it does not, we have the financing contingency, a renegotiation, or cash to close the gap.
Walkthrough and funds
A last look to confirm everything is as it should be — no new damage, every inclusion accounted for. Your final figure and form of payment are confirmed before we sit down to close.
Numbers
Monthly payment, in plain view.
Estimated monthly
$5,741
Principal & interest$4,424
Property tax$1,167
Insurance$150
Down payment$175,000
Illustration only — not a pre-approval. Tax rates vary by municipality. I can connect you with a trusted lender.
Start with a conversation.
Tell me what you are looking for. I will tell you how we work, what the next step is, and whether I am the right representative for it.